

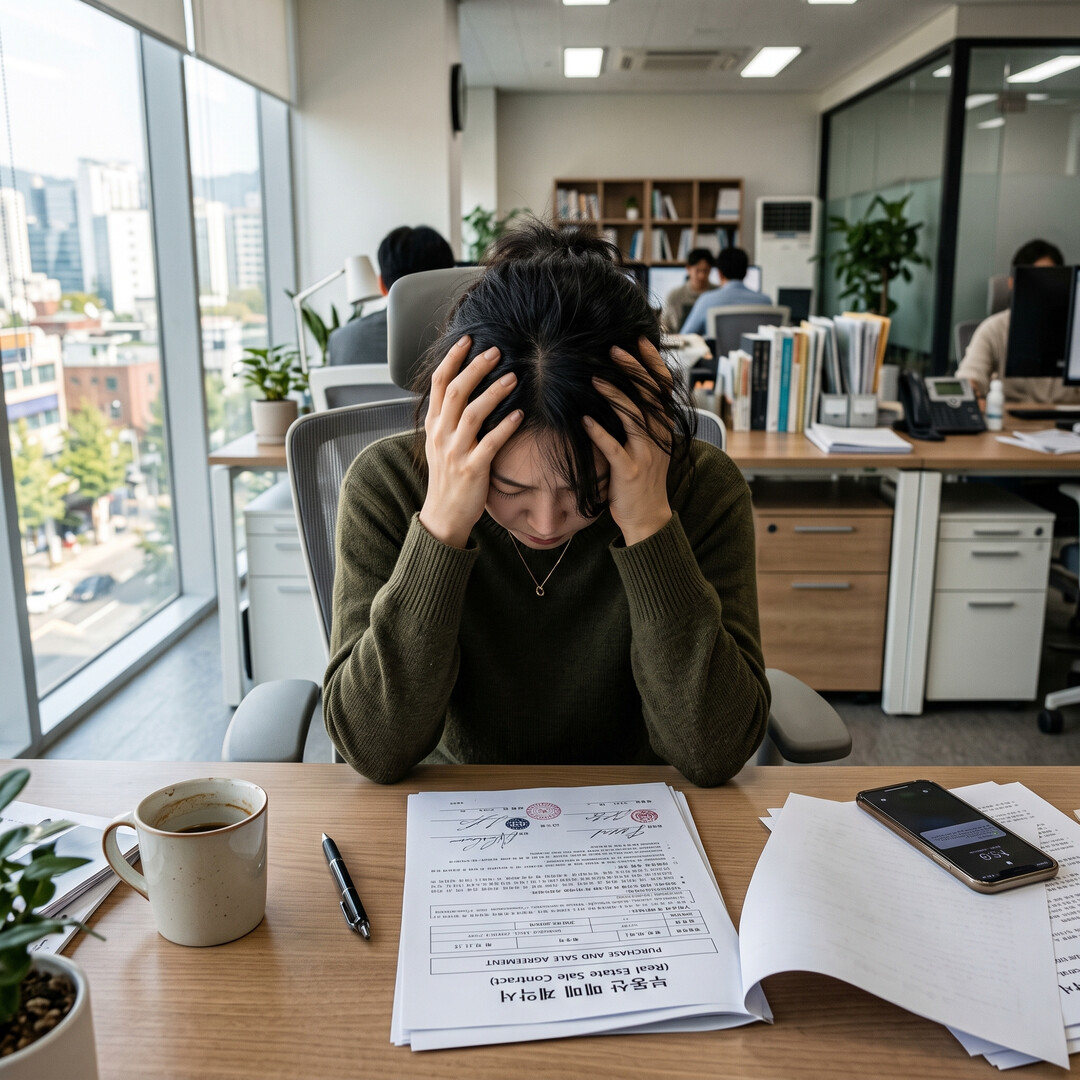
"I need to pay off my debts before I die." On the morning of the 21st, Mr. A, a man in his late 60s, hung his head at the Seoul Financial Welfare Support Center in Jung-gu, Seoul, as he applied for his third debt repayment extension. His restaurant, opened in 2016, suffered from sluggish sales coupled with heavy rent and labor costs, with monthly losses reaching up to 10 million won at one point.
Though he managed to survive for nearly eight years using bank credit loans, credit cards, and savings bank loans, liquidating the business left him with 50 million won in debt. Out of the 1.4 to 1.5 million won he now earns monthly as a school security guard, over 1 million won goes toward paying off his debt. Even as he asked for a postponement of repayments, he insisted that he would pay off his debt to the very end.
The center’s waiting room was packed with people waiting for consultation. The vast majority were middle-aged and older individuals with graying hair.
The way debt weighs down on people differs by generation. For generations in their 50s and 60s whose post-retirement incomes have dwindled—like Mr. A—debt piles up through card loans and insurance policy loans. According to the Bank of Korea (BOK), as of the end of the second quarter of this year, the average loan balance per vulnerable borrower aged 60 and older stood at 97.87 million won, more than double that of those aged 30 and younger. Conversely, for people in their 20s and 30s, delinquency rates are rising even as their card loan balances shrink.
Delinquencies are spreading across the financial sector as a whole. The bank loan delinquency rate hit 0.69% at the end of August, the highest for an August in 10 years, while delinquency rates for other household loans such as credit loans (0.91%) and private business loans (0.86%) also rose within a single month. On the 22nd, the BOK froze the benchmark interest rate, but with possibilities of a November hike being raised, the interest rate shock could intensify in the first half of next year.
4 in 10 of the Second Baby Boomers Face Zero Income Post-Retirement... The Interest Rate Hike Era’s "Debt Tsunami"
The debt of the elderly population outpaces other generations in both scale and growth rate. According to household debt database data submitted by the BOK to the National Assembly’s Strategy and Finance Committee, as of the end of the second quarter, the average loan balance per vulnerable borrower aged 60 and older (97.87 million won) exceeded those in their 50s (82.80 million won) and 40s (81.88 million won).
Vulnerable borrowers are defined as multiple-debtors who have borrowed from three or more financial institutions and either fall within the bottom 30% of income or have a credit score of 664 or lower. The proportion of vulnerable borrowers aged 60 and older rose from 15.0% at the end of 2021 to 19.9% by the end of the second quarter of this year, while household loan delinquency rates for those 60 and older more than doubled from 0.7% to 1.5% over the same period. Among vulnerable borrowers aged 60 and older, 25.8% had to pay annual principal and interest equal to or greater than their annual income—more than double the figure for those 30 and younger (11.4%).
Behind this trend are baby boomers retiring under a burden of debt. The second baby boom generation (born between 1964 and 1974), who have already retired or are facing retirement, number approximately 9.5 million. According to a 2023 survey by the Mirae Asset Retirement and Pension Center, while 78.8% of these workers support children or parents, 39% had no rental, pension, interest, or dividend income to rely on after retirement. As family support continues, a sudden cutoff in monthly salaries forces people to cut back on debt repayment funds first.
Card Loans Hit 39.5 Trillion Won... Largest Increase Among Those Aged 60 and Older
The debt of older adults who turned to self-employment for livelihood after retirement swelled even faster. Financial liabilities among self-employed individuals aged 60 and older surged more than fourfold from 96 trillion won at the end of 2015 to 405.7 trillion won in the first quarter of this year.
Of this, 167.5 trillion won consists of non-bank loans from mutual finance companies and savings banks, which carry higher interest rates than commercial banks. "The increase in debt among the elderly appears to be the result of a growing elderly population combined with sluggish performance in the self-employed sector," said Ahn Dong-hyun, a professor of economics at Seoul National University. "There are mounting concerns that older adults continuing businesses or starting new ventures for survival post-retirement will face escalating debt burdens."
Urgent liquidity demands are also manifesting in card loans and insurance policy loans. According to data submitted by the Financial Supervisory Service to People Power Party lawmaker Lee Jong-wook, the balance of card loans across eight specialized card companies reached 39.5207 trillion won at the end of July, up 418.3 billion won (1.1%) from the end of last year.
Over the same period, card loans for those aged 60 and older grew by 700.5 billion won (6.9%), and for those in their 50s by 285.3 billion won (2.1%), meaning the combined increase for the 5060 demographic outpaced the total national increase. For all other age groups, balances actually declined. Compared to the end of 2023, the balance for those aged 60 and older has increased by about 3.5 trillion won. Insurance policy loans, which allow borrowing against surrender values, also saw balances grow by 10.2% for those 60 and older to reach 13.1546 trillion won, and by 4.5% for those in their 50s. Conversely, balances for both types of loans declined among those in their 20s and 30s.
"People aged 60 and older face structural problems where declining post-retirement incomes make it difficult to utilize bank loans," said Kim Sang-bong, a professor of economics at Hansung University. "The more they rely on high-interest loans, the heavier the principal and interest burden becomes, deepening financial vulnerability."
Mr. A also began with bank credit loans before dragging himself into savings bank loans. "It was like pouring water into a bottomless pit," he recalled. "If I had made the decision to close down the business sooner, I wouldn't have ended up here. Looking back, there are many regrets." Although the Credit Counseling and Recovery Service (CCRS) debt adjustment eased his interest burden, it remains a heavy struggle to pay off the principal with his reduced income.
Another 60-year-old man visiting the center on the same day revealed that arrears on bank debts he had failed to repay for nearly 20 years had pushed his interest payments higher than the original principal. Living in a gosiwon (budget micro-dormitory) on basic livelihood security subsidies and taking on construction site jobs two or three times a month, he applied for debt adjustment once again.
Older adults who try to endure through debt only to find it completely unmanageable ultimately knock on the doors of courts and the CCRS. According to Supreme Court data, personal rehabilitation applications surged 15.2% year-on-year to 149,147 cases last year. Applicants aged 60 surged 3.8-fold from 3,922 in 2020 to 14,775 last year, while those aged 70 and older jumped 5.9-fold from 313 to 1,853. From January to July of this year, nearly four out of ten applicants (39.6%) were aged 50 or older. Confirmed rapid debt adjustment cases through the CCRS for those 70 and older jumped from 239 in 2022 to 1,684 last year, while those aged 60 rose more than fivefold from 1,015 to 5,339.
The Declining Repayment Capacity of the 2030 Generation
On the surface, the debts of individuals in their 20s and 30s appear to be shrinking. However, their capacity to repay is weakening at a much faster pace. Card loan balances for those in their 20s dropped by 4.8% compared to the end of last year, while those in their 30s saw a 4.6% decline. Yet, the delinquency rate for card loans among thirty-somethings rose from 2.42% at the end of last year to 2.96% in July of this year—the largest increase across all age groups.
For those in their 20s, it also climbed from 2.33% to 2.74%. This reads as a clear signal that while taking out new loans has become more difficult, an increasing number of borrowers are failing to repay existing debts on time. Debt adjustment applicants aged 39 or younger surged 64.8% from 40,979 in 2021 to 67,540 last year, and personal rehabilitation applicants in their 20s and 30s grew 32.2% from 36,248 to 47,920 over the same period.
Youth debt typically begins with shortages in living and housing expenses. Mr. B, a man in his 20s, found a job right after graduating from high school and moved out that autumn. His first debt was a loan to secure housing deposit money. After paying rent, utility bills, and loan principal and interest on a minimum-wage salary, his living expenses fell short. The gaps were patched up with micro-loans and credit cards; when repayment dates arrived, he used new loans to pay off old ones.
This debt-cycling continued for over five years. Approximately 49 million won of his final loan went entirely toward paying off pre-existing debts. Despite working without a break for seven years, his debt exceeded 70 million won, ultimately driving him to apply for personal rehabilitation.
The money he now earns as a dispatched worker amounts to little more than 2.1 million won per month. "Housing and living costs have risen so high that after subtracting basic living expenses from income, almost nothing is left to spend," said Song Kang, a representative attorney at Song Kang Law Office. "In that state, if you spend just six months to a year rolling over debts, situations quickly become unmanageable."
Investment losses can also spiral into unemployment and bankruptcy. Mr. C, a man in their 30s, even dragged in loan shark (private moneylender) loans to cover stock losses, but quit his job after debt collectors tracked him down to his workplace. Personal rehabilitation requires continuous or repetitive income. Having lost his source of income, he opted for bankruptcy instead of rehabilitation.
The greater concern is that the shock of interest rate hikes has not yet been fully reflected. According to a "Financial Stability Situation" report released by the BOK last month, benchmark interest rate hikes exert their greatest impact on bank lending rates with an approximate five-month lag, on total borrower delinquency rates with about a 15-month lag, and on vulnerable borrower delinquency rates with a roughly nine-month lag.
Considering consecutive rate hikes in July and August, delinquency pressures on vulnerable borrowers could heighten further in the first half of next year. Even with this month’s rate freeze, discussions surrounding a potential November hike threaten to make the burden heavier still.
The weakest links are already showing signs of shaking. In the second quarter of this year, the household delinquency rate for vulnerable borrowers was 26 times that of overall households, while vulnerable self-employed borrowers stood at 6.3 times that of overall self-employed individuals. The BOK estimates that a 0.25 percentage point increase in the benchmark interest rate swells household interest burdens by 3.3 trillion won and corporate burdens by 3.7 trillion won.
"Amid mounting interest burdens driven by rate hikes, sluggish domestic consumption continues, suggesting that hardships will persist into next year," said Joo Won, head of the Economic Research Department at the Hyundai Research Institute. "If falling asset prices—such as real estate and stocks—combine with this, even previously sound borrowers could degrade into vulnerable borrowers."
[Copyright (c) Global Economic Times. All Rights Reserved.]